
Business Planning & Strategy
How Much Does a Clothing Store Make?
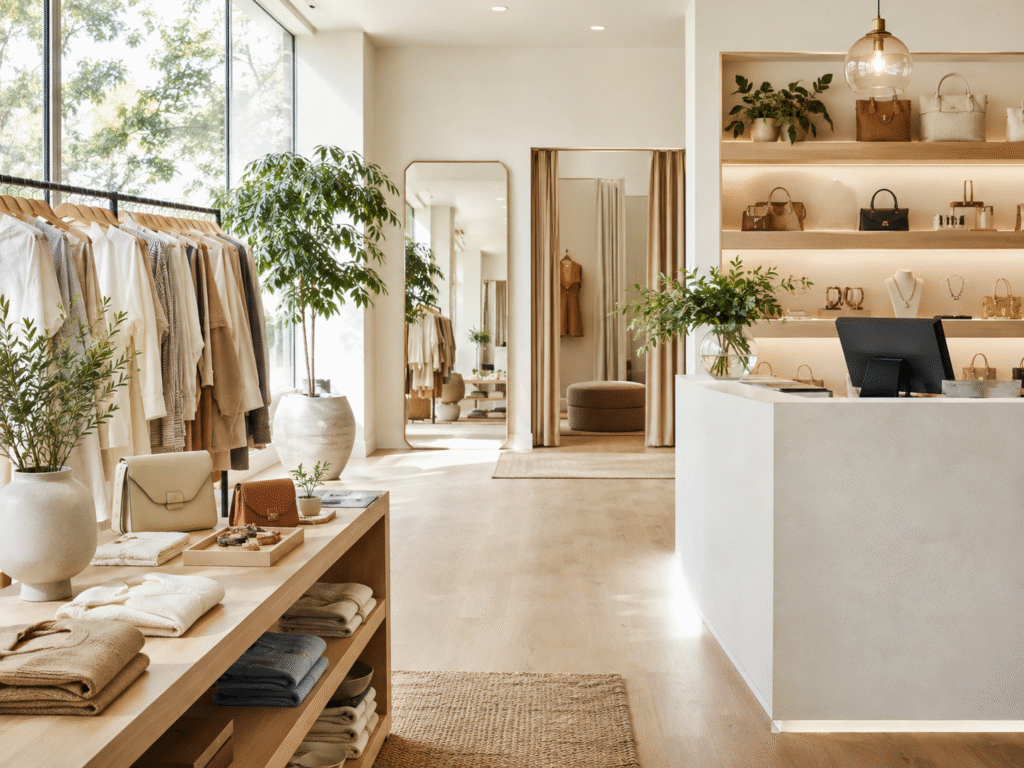
A clothing store is an inventory-velocity business where profit is decided by turnover, gross margin, and sales per square foot, not by how much stock fills the racks.
The model works when buying discipline, markup, and space productivity are engineered together, because merchandise is structurally the dominant cost and markdowns silently erode the margin that markup was meant to protect.
The trap is aged inventory. A garment carried too long gives back its margin to markdowns and carrying cost, which is why independent apparel net margins commonly sit at just 3% to 10%.
The numbers below model an established independent boutique of roughly 1,800 selling square feet in a mid-market location.
Asset Configuration
The economic question is not “how much inventory can the floor hold,” it is “how many times that inventory turns before it must be marked down.”
Apparel retail is moderately capital-light, so the constraint is rarely fixtures; it is the discipline to buy against real sell-through and keep the floor productive.
| Asset category | Lean boutique launch (USD) | Full retail buildout (USD) | What drives the number |
| Store fit-out, fixtures, fitting rooms | 30,000 to 80,000 | 80,000 to 200,000 | Selling area, finish level |
| Opening inventory (at cost) | 40,000 to 90,000 | 90,000 to 200,000 | Assortment breadth, price tier |
| POS, e-commerce, security | 8,000 to 20,000 | 20,000 to 50,000 | Omnichannel depth |
| Signage, lighting, visual merchandising | 8,000 to 25,000 | 25,000 to 70,000 | Brand positioning |
| Storefront deposit, permits, licensing | 10,000 to 30,000 | 30,000 to 80,000 | Location and lease terms |
| Launch marketing and working capital | 15,000 to 40,000 | 40,000 to 120,000 | Ramp to steady traffic |
A lean boutique opens for roughly 111,000 to 285,000 and a full buildout for 285,000 to 720,000. Because rent is fixed and unproductive floor space leaks margin, sales per square foot is the key stress test.
Formula: Sales per square foot = total revenue / selling area
Example: 540,000 / 1,800 = 300 per square foot
That sits mid-band against the 200 to 600 benchmark, but it only holds if inventory turns fast enough to avoid markdowns.
Revenue Model
Clothing is the base, but accessories carry disproportionate margin. Apparel commonly represents 70% to 85% of revenue, with accessories at 15% to 30% acting as high-margin add-ons.
Boutiques target a 50% to 60% gross margin using a markup of roughly 2 to 3 times cost, while inventory should turn 4 to 6 times per year.
Core formulas:
Retail price = unit cost × markup multiple
Gross margin = (retail price − unit cost) / retail price
Inventory turnover = cost of goods sold / average inventory at cost
Worked example for a single unit and the store’s stock:
Retail price = 40 × 2.2 = 88
Gross margin = (88 − 40) / 88 = 54.5%
Inventory turnover = 240,000 / 48,000 = 5.0 times per year
| Revenue stream | Assumption | Annual revenue (USD) |
| Clothing (in-store and online) | ~78% of sales | 420,000 |
| Accessories (jewelry, bags, belts, hats) | high-margin add-ons | 100,000 |
| Alterations, gift cards, other | mixed | 20,000 |
| Total | 540,000 |
Accessories punch above their revenue share because they carry higher margins and lift average transaction value, which is why floor space allocated to them is rarely wasted.
Operating Costs
A clothing store is a cost-of-goods business first and a payroll business second. Merchandise runs near half of revenue, and operating expenses typically consume 25% to 35% of sales.
The line owners underweight is the markdown, which converts unsold inventory into recovered cash at a fraction of intended margin.
Start with the merchandise and what it realizes after markdowns.
Realized gross margin = (net sales − cost of goods sold) / net sales
Now cost the full operation.
| Cost category | Annual cost (USD) | Notes |
| Cost of goods sold | 240,000 | About 44% of revenue after markdowns |
| Payroll (owner-manager, sales staff) | 120,000 | Scheduled to traffic |
| Rent | 45,000 | About 8% of revenue |
| Marketing | 26,000 | Social, events, loyalty |
| Software and card processing | 23,000 | POS, e-commerce, merchant fees |
| Inventory carrying, supplies, packaging | 15,000 | Bags, tags, hangers |
| G&A and contingency | 12,000 | Discipline matters |
| Utilities | 12,000 | Lighting, climate |
| Depreciation (fixtures, buildout) | 10,000 | Fit-out amortization |
| Insurance and licensing | 8,000 | Risk and compliance |
| Total operating costs | 511,000 |
Profit math:
Operating surplus = Total revenue − Total operating costs
Operating surplus = 540,000 − 511,000 = 29,000
Operating margin = 29,000 / 540,000 = 5.4%
Gross margin holds at 55.6%, but overhead and markdowns compress it to a 5.4% operating result, with the owner-manager salary already inside payroll, so owner total take lands near 84,000.
Independent stores typically net 3% to 10%, while top boutiques reach 12% to 15%, so the base case sits mid-band with upside from turnover and margin discipline.
Break-even shows how little room the model leaves.
Variable cost ratio = (COGS + processing + packaging) / revenue = 268,000 / 540,000 = 49.6%
Contribution margin ratio = 1 − 0.496 = 50.4%
Break-even revenue = Fixed costs / contribution margin ratio
With a largely fixed base of about 243,000 (payroll, rent, marketing, utilities, core software, depreciation, insurance, G&A):
Break-even revenue = 243,000 / 0.504 = 482,143
Against 540,000 in sales, the store clears break-even by roughly 58,000, or about 268 per square foot against 300 actual.
That slim margin of safety is why turnover and gross margin, not raw footfall, decide whether the year ends in profit.
Profitability Strategies
These levers only work once the model is aligned: tight buying, disciplined markup, and a floor that sells through before the season turns.
The goal is to widen the spread between realized gross margin and the cost of holding inventory, then multiply it through faster turns and higher space productivity.
1. Turn inventory faster and kill markdowns
Because a garment gives back margin the longer it sits, turnover is the highest-return lever in the business.
Buy in tighter, more frequent drops against real sell-through data, exit aging stock decisively before it demands deep discounts, and track weeks-of-supply by category.
Moving turnover from 5 to 6 times a year on the same floor lifts sales without new space and cuts the markdowns that quietly consume net margin.
2. Protect and lift gross margin
Markup discipline is where profit is set, so hold the 2 to 3 times multiple and resist reflexive discounting that trains customers to wait for sales.
Weight the assortment toward accessories and specialty categories that carry higher margins and lower price sensitivity, and pursue exclusive or private-label lines that remove direct price comparison.
Every point of realized margin held is worth more than a point of extra sales, because it flows straight past variable cost.
3. Raise sales per square foot
Rent is fixed, so the floor must work harder rather than larger. Merchandise to the productive zones, cross-sell complementary items through adjacency and outfitting, and lift average transaction value with attachments at the register.
Reallocating slow-selling square footage to proven categories raises revenue per square foot without adding rent, which drops almost entirely to contribution.
4. Add channels and diversify demand
A single storefront is exposed to local footfall, so extend reach without extending the lease. Layer e-commerce and social selling onto the same inventory, build a loyalty program that lifts repeat purchase, and use in-store events and styling appointments to convert traffic at higher value.
Omnichannel demand smooths seasonal swings and improves sell-through on the stock you already carry.
5. Control operating and rent leakage
Operating expenses at 25% to 35% of sales leave little slack, so audit the lines that scale poorly. Hold rent to a defined share of revenue at renewal, schedule payroll to actual traffic patterns rather than fixed shifts, and manage merchant fees and software subscriptions annually.
Each point trimmed from overhead is permanent margin that does not depend on selling a single additional garment.
So what?
A clothing store can deliver a respectable owner income, but only when it is run as an inventory-velocity business rather than a curated collection that sits pretty on the rack.
The practical path is to turn stock faster, hold markup discipline against markdowns, and drive sales per square foot through merchandising and channel mix, then push from the typical 3% to 10% net toward the 12% to 15% that top boutiques achieve.
The operators who win manage the spread between realized gross margin and inventory carrying cost, turn by turn, season by season.
If you want to estimate revenue, costs, and profit using real inputs (sales per square foot, markup, inventory turnover, payroll, and rent), use a clothing store financial model to run the numbers fast.